Skip to main contenthow this is calculated →
Year 5 disposal

BMV -35%
⊞ View all 15
16/ 100
Weak
6.81% Rent by the room return before costs — verify the rent + comps locally.
Why it works
- Priced below market -35% vs 12 nearby sold (last 12 mo) — instant equity
Why to be cautious
- EPC D — must hit C by 2030 (~£3,000–£7,000)
- Monthly profit −£582/mo — heavily negative — needs monthly capital injection
- -5.9% 5y IRR — capital outlay disproportionate to returns
- No rent comparables — estimate is a rule-of-thumb fallback, not market data. Verify the rent locally before offering.
Property research tool — not a regulated financial service. Numbers are point-in-time estimates; how we decide →
Monthly cashflow
−£582/mo
You top up £582/mo
Price vs market
Below market value
-35% vs 12 sold · interior unseen
Return · IRR
-5.9%/yr
Loses money over 5 years
Cash left in
£0
Fully recycled — pull all your cash back out
Price £325KCash to buy £127KReturn before costs on price · Rent by the room 6.81%5-yr return on cash -23%Rent est. £1,206 (£1,134–£1,283)
How we define each return: On price — gross yield = annual rent ÷ purchase price. On cost — net yield ÷ total project cost (price + refurb + fees). On cash — cash-on-cash & ROI ÷ the actual cash you put in (deposit + costs).
What-if calculator
Rates as of 20 May 2026Buy-to-Let. Standard rental on an Assured Shorthold Tenancy. Single household, market rent, paid monthly direct to landlord (or via agent). (hover any strategy tab for pros + cons)
Offer (£)
Monthly rent (£)
Local comp range: £1,134–£1,283/mo · n=61
Financing
DepositYour cash in — the rest is the mortgage25% · £81,250
Standard 75% LTV for BTL
Mortgage rate5y fixed5.8%
5-year fixed at 75% LTV — 5.75% (as of 2026-05-20).
Mortgage term (years)
Stress rate6.5%
BoE base + 2pp stress (6.5%)
Acquisition costs
Refurb (£)
Per-property refurb estimate from the element rate-card model (£11,333–£21,155 range), VAT-inclusive
Legal + survey (£)
Standard house — £1,400 legal + £750 survey
Mortgage fees (£)
2% product fee on £243,750 loan + £1,000 booking fee
Running costs
Management10%
Typical BTL agency rate
Void weeks
Typical voids for BTL
Insurance (£/mo)
Typical BTL building+landlord cover for £200K–£400K
Maintenance (£/mo)
Detached: £100/mo proxy (more roof + grounds)
Leasehold costs
Result · Rent it out
Monthly profit
-£582
after mortgage, operating costs & tax
Rent in£1,206/mo gross
£1,160/mo collected · £46/mo lost to voids
Where it goes
£1,320Mortgage£422Costs
Outgoings exceed rent — you top up £582/mo
Mortgage£1,320
Costs£422
Management£121
Maintenance£100
Insurance£28
CapEx reserve£60
Voids + council tax£9
Ltd co. accounts£104
Tax—
Shortfall−£582
Returns
Return before costs on price4.45%
Cash return on cash-5.51%
Gross margin£738
Cash needed£126,886
Monthly profit paybackn/a (monthly loss)
Data confidence
Lender stress test
Rent-covers-mortgage check @ stress0.88
Rent-covers-mortgage check FAIL · stress 6.5% (need ≥ 1.45)
Year-by-year Monthly profit (5-yr horizon)
Net Monthly profit after tax. Rent + costs compound at their growth rates; mortgage principal amortises year-by-year for repayment loans.
Mortgage paydownRent profitbefore price growth
Full year-by-year breakdown
| Year | Gross Rent | Op Costs | Mortgage | Equity Built | Tax | Net | Cumulative |
|---|---|---|---|---|---|---|---|
| Year 1 | £14,472 | £5,060 | £15,844 | £0 | £0 | -£6,432 | -£6,432 |
| Year 2 | £14,906 | £5,212 | £15,844 | £0 | £0 | -£6,149 | -£12,581 |
| Year 3 | £15,353 | £5,368 | £15,844 | £0 | £0 | -£5,858 | -£18,439 |
| Year 4 | £15,814 | £5,529 | £15,844 | £0 | £0 | -£5,559 | -£23,998 |
| Year 5 | £16,288 | £5,695 | £15,844 | £0 | £0 | -£5,250 | -£29,248 |
Disposal gain (gross)-£14,905
CGT£0
Net Disposal proceeds£349,856
What we verified
What we verified
51065 ok · 1 caution · 0 fail · 6 unknown
Legal & planning
LeaseholdFreehold
Tenure & planningFreehold
Legal & planning
2 checks- TenureUnknown
- Lease lengthUnknown
Council planning restrictionUnknown
Council planning restrictionRent by the room conversion gatePlanning data
Rent by the room restriction
C3 to C4 conversion
Unknown
Confidence
low
Source
No LPA data for this prefix
Rates as of May 2026
Building condition
Energy ratingD
EPC& 2030 deadlineEPC register
▼
ABCDEFG
Current rating
From listing descriptionBand D
MEES 2030 compliance
C required for new tenancies
FAIL
Upgrade to C
estimated cost
£3k–£7k
EPC band from listing · verify certificate before exchanging
Find EPC certificate →Cladding safety certificateNot stated on the listing
HeritageNot stated on the listing
Heritage& planning constraintsNHLE register
We don't ingest the NHLE bulk register, so we can't flag listed-building or conservation-area status for this address from our data alone. Use the official registry to verify before exchanging.
Area
Flood riskChecking…
FloodriskEA
Crime riskChecking…
Crimeriskpolice.uk
SchoolsChecking…
Schools& Ofsted catchmentGIAS register
No schools indexed for this postcode sector.
Investor
Tenant profileFamily let
Tenant profilelikely cohortTQ5 0QA · 3 bed
Primary profile
Family let
Nearest university
for student-let assessment
University of Exeter · 37.8 km
Reason
3-bed house in a suburban area — family-let demand dominates; check local school catchment ratings.
Heuristic from postcode + bedrooms + nearest-university distance · verify locally
Refurb costEstimate ready
Refurb cost& works budgetQ1 2026 rates
New kitchen + bathroom + light replumb + decor.
Total estimate
3-bed · 2-bath · 990 sqft
£28k–£56k
£ per sqft
building cost only
£29–£56
Per-item breakdown (4 lines)
- Kitchen · Full unit replacement£3,840–£8,640
- 2 × bathroom · Full strip + retile£6,650–£13,300
- Paint + decor£6,930–£12,870
- Flooring · Carpet on bedrooms + LVT/laminate downstairs£10,890–£20,790
Guide rates · UK May 2026 · sqft auto-estimated from beds
Tier-based bands — get a builder quote before exchanging.
Rent by the room licensingStandard rules
HMO licensing5-year licenceCouncil
Licence fee
5-year mandatory
£825–£1,500
Scheme type
Check council
The council's HMO page lists the current mandatory fee plus any additional / selective scheme that catches smaller HMOs.
Mandatory licensing applies to 5+ sharer HMOs (Housing Act 2004)
Find council HMO page →Price & sale history117d on market1 price change
Sale price historythis address, HM Land RegistryPrice-Paid Data
Asking vs last sale
£232,500 in 2012 → £325,000 asking
+39.8%in 14y
- 2012£232,500+196.2% in 17y
- 1995£78,500—
HM Land Registry · Price-Paid Data (Open Government Licence). Growth percentages are nominal — not adjusted for inflation or local market movement.
Strategy matrix
Rent by the room wins — +£580/mo · £697/mo ahead of Short-stay let / Airbnb (after room-conversion)
| Strategy | Return before costs on price | Monthly profit | Cash needed | 5y Return on your cash on cash | Risk | Feasibility |
|---|---|---|---|---|---|---|
| Rent it out | 4.45% | -£582 | £126,886 | -23.1% | Low | Feasible |
| Housing-benefit rent | 3.09% | -£939 | £126,886 | -40.0% | Med | Feasible |
| Council lease | 3.09% | -£756 | £126,886 | -34.1% | Low | Feasible |
| Refurb & refinance | 4.45% | -£582 | £149,180 | -19.6% | Med | Feasible |
| Short-stay let / Airbnb | 9.45% | -£117 | £126,886 | -1.8% | High | Feasible |
| Buy, improve & sell | 0.00% | -£232 | £370,805 | 5% | Med | Feasible |
| ⭐ Rent by the room | 5.35% * | +£580 | £136,757 | — | — | Feasible |
* Rent by the room shows net yield on cost for the audited HMO conversion deal (post-conversion, after running costs) — not gross like the other rows. Its 5-yr ROI reads “—” because the audited deal is a year-one snapshot; the HMO conversion panel below shows the cash-back / payback horizon.
Short-let (SA) context325 active short-lets nearby
Short-let market context
- 325 active short-let listings in this postcode
Housing-benefit (LHA) scheme detailBRMA South Devon · cap £838/mo
Housing-benefit rent scheme detail
- Rental Market Area (BRMA):
- South Devon
- LHA monthly cap:
- £838
- Scheme type:
- other
- Premium:
- +0% premium over LHA cap
- Management:
- management covered by council
Ready to move on this deal?
Generates an offer pack with your numbers & sources — take it to the agent.
Pro analysis — outcome range, stress tests & portfolio impact
Local lettings demanddays-to-let · supply now · trend
Local lettings demandby strategyLive area data
Short-stay let55% occupancy
£152/night ADR
Based on 16 short-let comps nearby
Rent by the room conversion upside
+£237/mo cash flow vs Rent it out if converted to Rent by the room
8.86% Return before costs on price converted vs 4.45% as-is
£325k → 5-bed HMO @ ~£615/room: £2,984 pcm gross, ~£1,697 pcm net (5.3% net on £381k all-in incl. ~£31k works); GDV ~£263k → refinance releases ~£-47k (~£183k left in)
medium confidence
Unlocks ~£14,760/yr extra rent
3 → 5 lettable rooms · ~5.7% gross at max
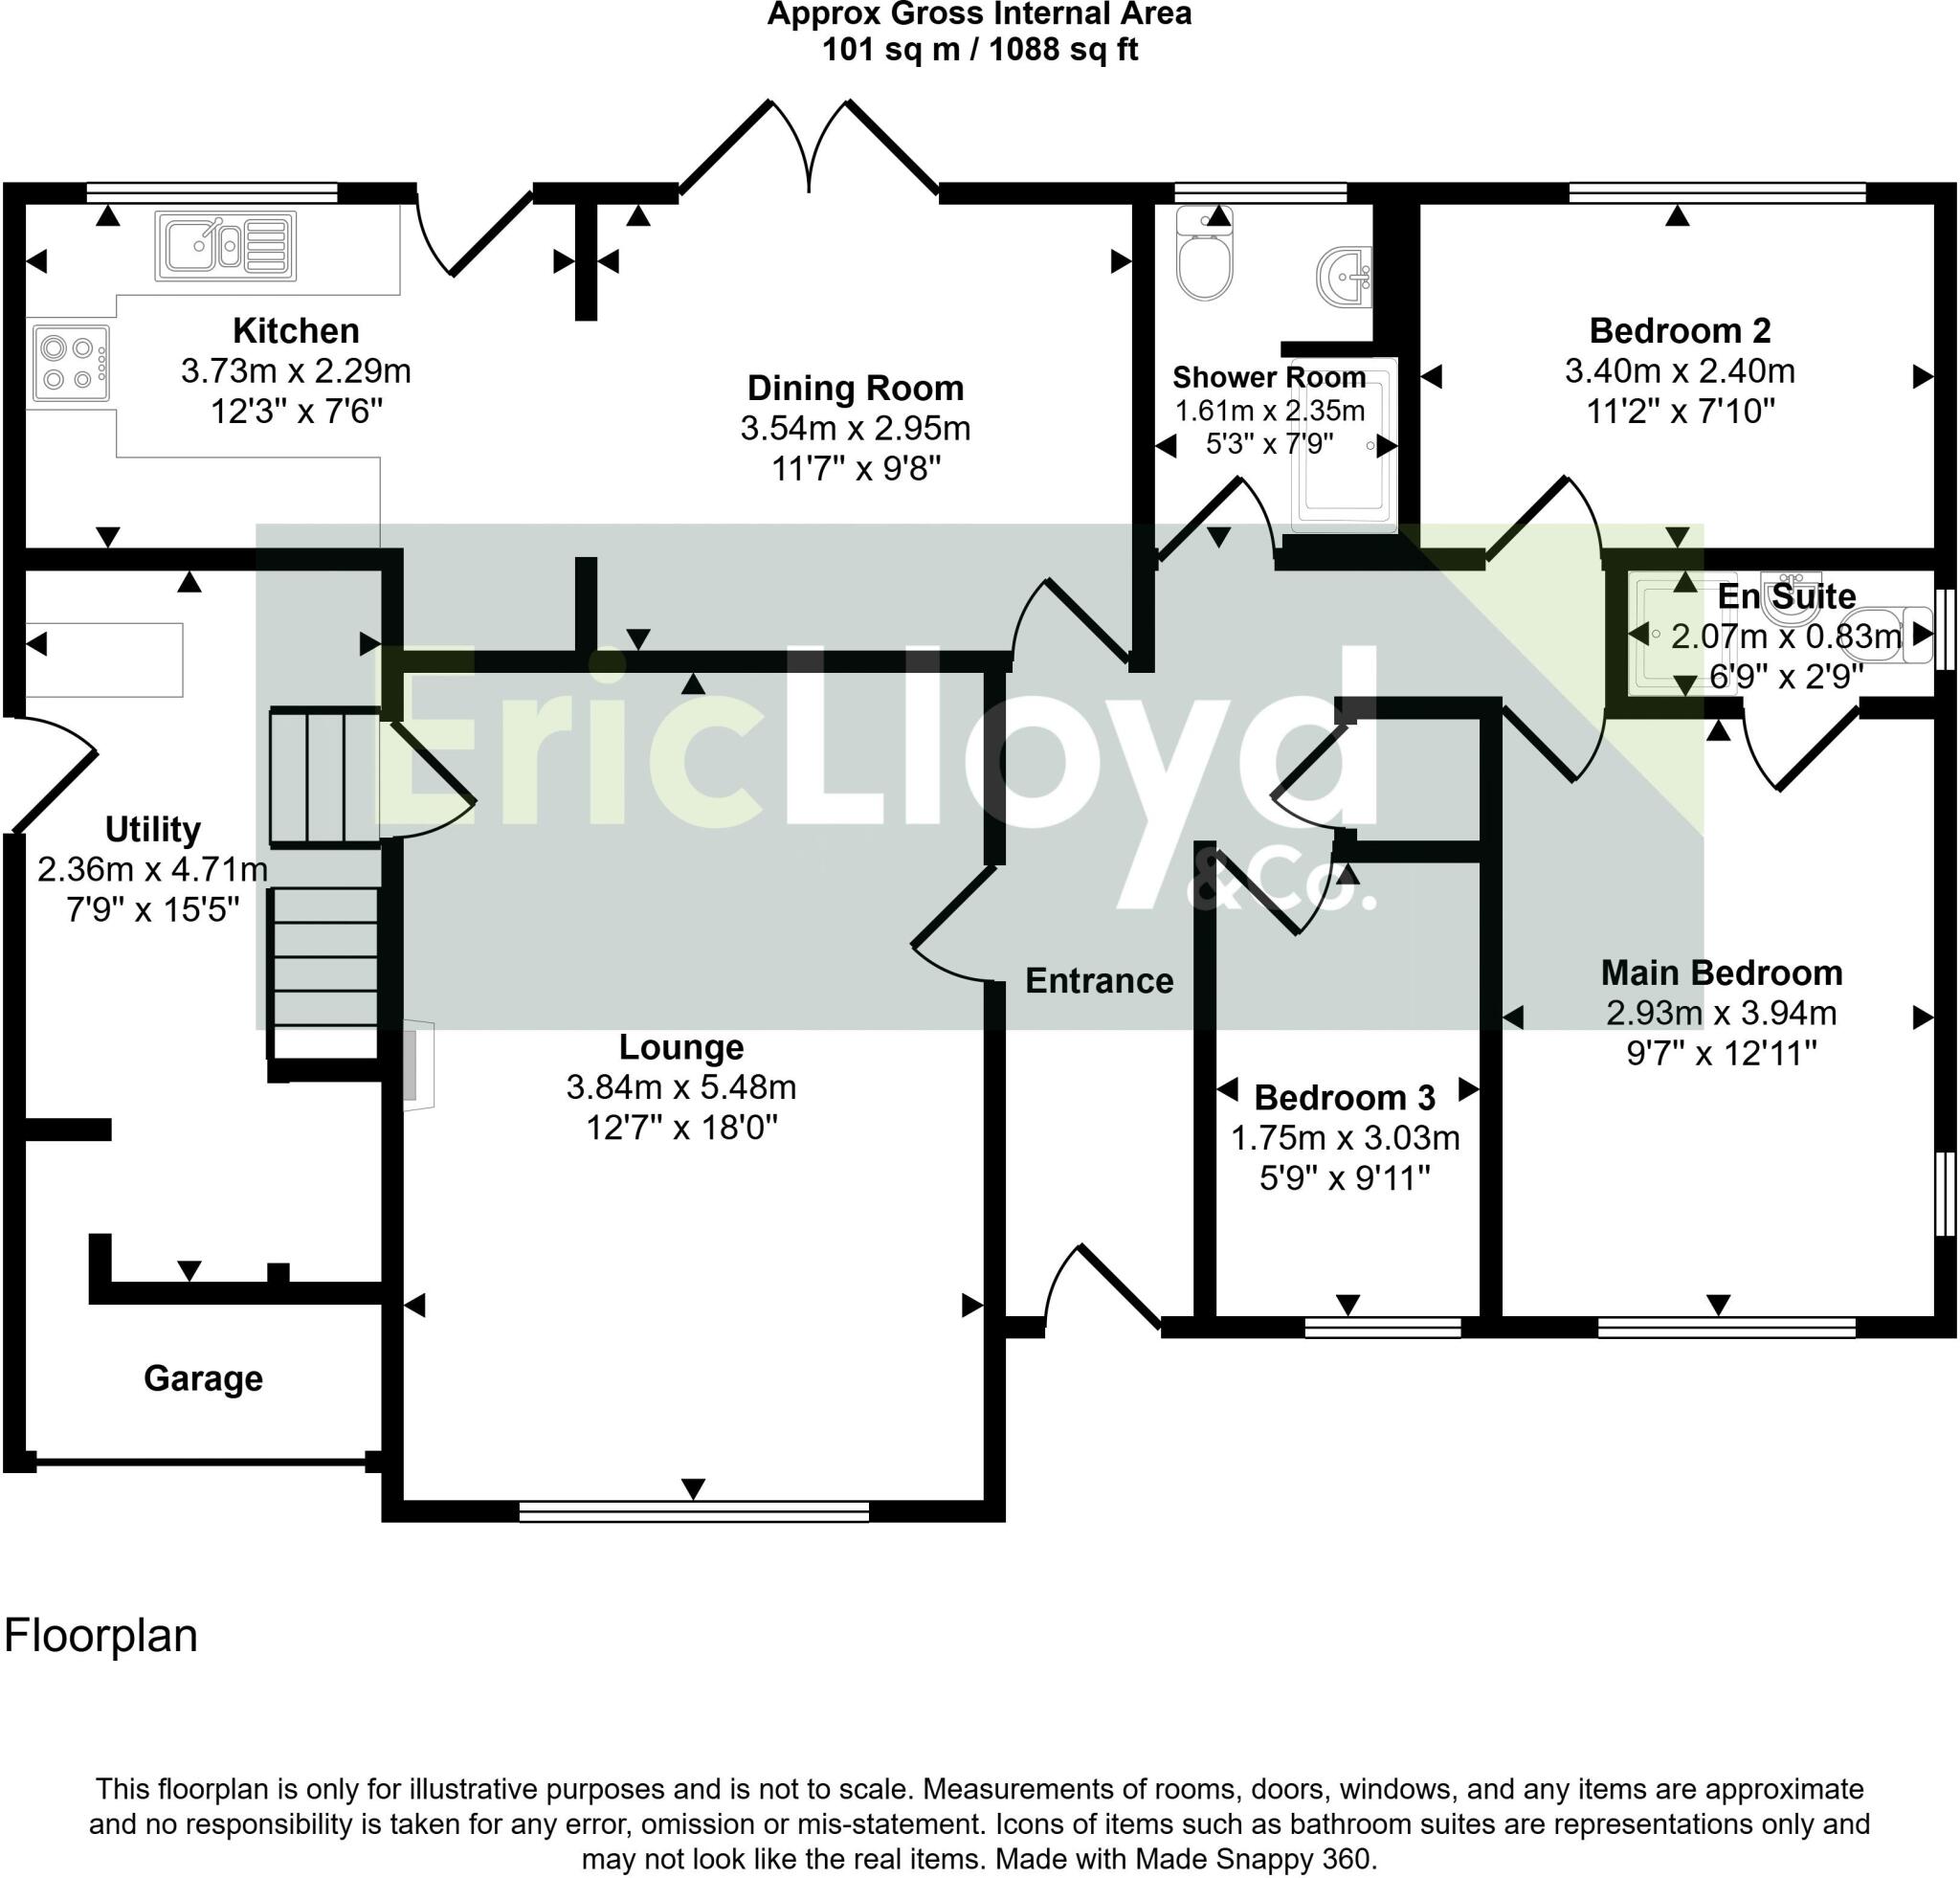
Potential, not guaranteed (subject to planning + regs). Estimate from the floorplan (kitchen size assumed) — verify room sizes against the floorplan before offering.
How we calculated this
floorplan shows 6 habitable rooms (3 beds + 3 reception(s)) in 101 m²; convert 2 spare room(s) to bedrooms, keeping one reception as the lounge → up to 5 lettable rooms (1 double, 0 single) (incl. the garage — convertible to a bedroom or the communal area); sized to Torbay adopted standard (6.51/10.22 m²; House in Multiple Occupation (HMO) Standards, Torbay Council, November 2019); 1 room size(s) not printed on the plan — counted but unverified vs the standard; adds ~£1,230/mo; loft conversion may add 1-2 further rooms (subject to head height/planning — not counted); mandatory HMO licence (5+ persons, England)
🔒 Room-add markup · Pro
Pro members see the floorplan with every convertible room outlined in green. Verify room sizes before offering.
3 → 5 bed HMO+1 double, +1 single5.35% net on cost5.09% cash-on-cashuplift 4.45% → 5.74%
💷 Refinance could release ~-£46,644
HMO licence
Sized to Torbay's adopted HMO standards
Projections use documented assumptions (local room rates, typical conversion costs, 75% LTV at 5.5%, indicative regional valuation yields) and each council’s published HMO standards. Not financial advice. Verify room sizes, licensing and planning with the council and a surveyor before purchase.
Room mix (3 lettable rooms)
3× Double @ £615/mo
≈ £1,845/mo gross room income
As-is Rent it out
Monthly profit-£494
Return before costs on price4.45%
Cash needed£93,148
If converted to Rent by the room
Monthly profit-£257
Return before costs on price8.86%
Cash needed£109,148
Δ vs Rent it out Monthly profit+£237
+2 rooms (5 total)
Monthly profit+£187
Return before costs on price11.35%
Cash needed£129,148
Extra rent+£1,230/mo
Show conversion detail
Conversion cost estimate
£44,000
Range: £38,000 – £52,000
Fire safety, plumbing, partitioning, licensing.
Rates as of Apr 2026
£54,690–£102,530full refurb + room split
What's in this cost
- Kitchen£8,640–£17,280
- 2 × bathroom£11,400–£20,900
- Rewire£3,960–£6,930
- Replumb£2,970–£5,940
- Windows£9,900–£17,820
- Paint + decor£6,930–£12,870
- Flooring£10,890–£20,790
Based on 86 HMO comps within 7.9 km
Comparables
sold within 0.5 miWide · CV 33.1%Med confidence
Loading nearby sold…
Location & area intelligence
Transport score100 / 100
On the map
- Registered HMOs
- Approved HMO conversions
- Pending HMO applications
Schools & catchment3 schools nearby
Nearby schoolsOfsted-rated, nearest first3 of 5
- OutstandingGalmpton Church of England Primary SchoolPrimary · Academy converter · TQ5 0LT
- GoodSt Margaret Clitherow Catholic Primary SchoolPrimary · Academy converter · TQ5 0EE
- GoodChurston Ferrers Grammar School AcademySecondary · Academy converter · TQ5 0LN
Ofsted · postcode-area match. Catchment areas vary year to year — verify with the local council before relying for school admissions.
Tax treatment
Annual gross rent£14,472
Section 24 credit£0
Annual tax due£0
Post-tax Monthly profit annual-£6,988
Exit costs
Projected sale price (5y · 2%/yr growth)£358,826
Capital gain (pre-CGT)£33,826
Sale costs (~2.5%)£8,971
CGT due (Ltd Co 25%)£0
No personal CGT — the gain is taxed at the company level (corporation tax) when the SPV disposes of the property.
Net 5y Monthly profit after CGT-£29,248
Rates as of Oct 2024
Acquisition costs
£126,886cash neededPurchase price£325,000
Deposit (25%)£81,250
Stamp duty+5% additional-property surcharge£22,500
Refurb£15,111
Legal + survey£2,150
Mortgage fees£5,875
Total cash neededdeposit + costs (loan covers the rest)£126,886
Green = verified data. Amber = market typical. Red = our estimate — verify before offering.
About this propertydescription · rightmove
Description& agent copyRightmove
Situated in a quiet and private cul-de-sac within the highly regarded Churston area, this THREE BEDROOM DETACHED BUNGALOW offers comfortable single-level living in a convenient and sought-after residential setting. Available for sale with NO ONWARD CHAIN, the property combines generous accommodation with attractive, low-maintenance gardens, making it an ideal choice for a variety of purchasers including retirees, downsizers and those seeking a lock-up-and-leave home.
The ac…
Floor plans
Nearby active comparables5 deals
Comparable rentals
TQ5 · same beds + typeNo nearby rentals matched on postcode prefix + bedrooms + property type.
Listing metarightmove · Eric Lloyd & Co
About this listing
117 days · RightmovePrice history
5-year price trend
Monthly profit
−£582
Cash needed
£127K
Return after costs
-5.51%
IRR
-5.85%
Listed 117d ago
CAMELLIA CLOSE CHURSTON
detached · 3 bed · 2 bath
£325,000
est £1,206 · 4.45% gross
EPC D
Priced below market
1 / 15
16/100
Marginal
6.81% — verify the rent + comps locally.
Priced below market -35% vs 12 nearby sold (last 12 mo)
Energy rating D — must hit C by 2030 (~£3,000–£7,000)
Price
£325K
35% below sold comps
Return before costs (best)
6.81%
Rent by the room
Bedrooms
3
2 bath
Energy rating
D
Energy rating
Deal flags1 issue
EPC D — upgrade by 2030
Must reach EPC C by 2030 to let on a new tenancy
Run the numbers
What-if calculator
Rates as of 20 May 2026Buy-to-Let. Standard rental on an Assured Shorthold Tenancy. Single household, market rent, paid monthly direct to landlord (or via agent). (hover any strategy tab for pros + cons)
Offer (£)
Monthly rent (£)
Local comp range: £1,134–£1,283/mo · n=61
Financing
DepositYour cash in — the rest is the mortgage25% · £81,250
Standard 75% LTV for BTL
Mortgage rate5y fixed5.8%
5-year fixed at 75% LTV — 5.75% (as of 2026-05-20).
Mortgage term (years)
Stress rate6.5%
BoE base + 2pp stress (6.5%)
Acquisition costs
Refurb (£)
Per-property refurb estimate from the element rate-card model (£11,333–£21,155 range), VAT-inclusive
Legal + survey (£)
Standard house — £1,400 legal + £750 survey
Mortgage fees (£)
2% product fee on £243,750 loan + £1,000 booking fee
Running costs
Management10%
Typical BTL agency rate
Void weeks
Typical voids for BTL
Insurance (£/mo)
Typical BTL building+landlord cover for £200K–£400K
Maintenance (£/mo)
Detached: £100/mo proxy (more roof + grounds)
Leasehold costs
Result · Rent it out
Monthly profit
-£582
after mortgage, operating costs & tax
Rent in£1,206/mo gross
£1,160/mo collected · £46/mo lost to voids
Where it goes
£1,320Mortgage£422Costs
Outgoings exceed rent — you top up £582/mo
Mortgage£1,320
Costs£422
Management£121
Maintenance£100
Insurance£28
CapEx reserve£60
Voids + council tax£9
Ltd co. accounts£104
Tax—
Shortfall−£582
Returns
Return before costs on price4.45%
Cash return on cash-5.51%
Gross margin£738
Cash needed£126,886
Monthly profit paybackn/a (monthly loss)
Data confidence
Lender stress test
Rent-covers-mortgage check @ stress0.88
Rent-covers-mortgage check FAIL · stress 6.5% (need ≥ 1.45)
Short-let (SA) context325 active short-lets nearby
Short-let market context
- 325 active short-let listings in this postcode
Housing-benefit (LHA) scheme detailBRMA South Devon · cap £838/mo
Housing-benefit rent scheme detail
- Rental Market Area (BRMA):
- South Devon
- LHA monthly cap:
- £838
- Scheme type:
- other
- Premium:
- +0% premium over LHA cap
- Management:
- management covered by council
Year-by-year Monthly profit (5-yr horizon)
Net Monthly profit after tax. Rent + costs compound at their growth rates; mortgage principal amortises year-by-year for repayment loans.
Mortgage paydownRent profitbefore price growth
Full year-by-year breakdown
| Year | Gross Rent | Op Costs | Mortgage | Equity Built | Tax | Net | Cumulative |
|---|---|---|---|---|---|---|---|
| Year 1 | £14,472 | £5,060 | £15,844 | £0 | £0 | -£6,432 | -£6,432 |
| Year 2 | £14,906 | £5,212 | £15,844 | £0 | £0 | -£6,149 | -£12,581 |
| Year 3 | £15,353 | £5,368 | £15,844 | £0 | £0 | -£5,858 | -£18,439 |
| Year 4 | £15,814 | £5,529 | £15,844 | £0 | £0 | -£5,559 | -£23,998 |
| Year 5 | £16,288 | £5,695 | £15,844 | £0 | £0 | -£5,250 | -£29,248 |
Rent by the room upside
What we verified
5106
Legal & planning▾
Article 4HMO restriction lookupUnknown
Rent by the room licensingMandatory if 5+ unrelatedCheck LPA
TenureTenure typeFreehold
HeritageListed building / conservation areaNot stated on the listing
Building condition▾
EPC~£3,000–£7,000 to upgrade to CD
EWS1External wall safety (cladding)Not stated on the listing
Refurb costBased on beds + baths + sqftEstimate available
Area▾
Crimepolice.uk · monthlyChecking…
SchoolsGIAS · OfstedChecking…
FloodEA Flood Map · England onlyChecking…
Investor profile▾
Tenant profileBeds + postcode heuristicFamily / Rent by the room
Rent by the room feasibilityMin 3 beds for C4 routeFeasible
Comparables
sold within 0.5 miWide · CV 33.1%Med confidence
Loading nearby sold…
Location & transport
Tax & exit
Tax bandLtd Co 25%
Mortgage-interest tax rule credit£3,169
Annual rental tax£0
CGT yr 5£0 · company level
5y net total-£29,248
Acquisition costs
25% deposit£81,250
Stamp duty£22,500
Refurb£15,111
Legal + survey£2,150
Mortgage + broker£5,875
Cash needed£126,886
Green = verified data. Amber = market typical. Red = our estimate — verify before offering.
Make an offer
Pro analysis — outcome range, stress tests & portfolio impact
Your notes
Description& agent copyRightmove
Situated in a quiet and private cul-de-sac within the highly regarded Churston area, this THREE BEDROOM DETACHED BUNGALOW offers comfortable single-level living in a convenient and sought-after residential setting. Available for sale with NO ONWARD CHAIN, the property combines generous accommodation with attractive, low-maintenance gardens, making it an ideal choice for a variety of purchasers including retirees, downsizers and those seeking a lock-up-and-leave home.
The ac…
Floor plans
Listing
Sources: Rightmove · HM Land Registry · Ofsted · EA Flood Zones
Estimates not financial advice
Estimates not financial advice