Skip to main contenthow this is calculated →
Year 5 disposal
BMV -25%
⊞ View all 9
13/ 100
Weak
5.45% return before costs — market rent unverified, verify rent + comps locally.
Why it works
- Priced below market -25% vs 12 nearby sold (last 12 mo) — instant equity
Why to be cautious
- Monthly profit −£296/mo — significantly negative — real recurring drain
- -3.7% 5y IRR — capital outlay disproportionate to returns
- No rent comparables — estimate is a rule-of-thumb fallback, not market data. Verify the rent locally before offering.
- EPC band not stated — verify the certificate before offering (2030 MEES minimum is band C).
Property research tool — not a regulated financial service. Numbers are point-in-time estimates; how we decide →
Monthly cashflow
−£296/mo
You top up £296/mo
Price vs market
Below market value
-25% vs 12 sold · interior unseen
Return · IRR
-3.7%/yr
Loses money over 5 years
Cash left in
£30K
Stays in after refinancing at value
Price £243KCash to buy £92KReturn before costs on price 5.45%5-yr return on cash -14%Rent est. £1,101 (£1,054–£1,150)
How we define each return: On price — gross yield = annual rent ÷ purchase price. On cost — net yield ÷ total project cost (price + refurb + fees). On cash — cash-on-cash & ROI ÷ the actual cash you put in (deposit + costs).
What-if calculator
Rates as of 20 May 2026Buy-to-Let. Standard rental on an Assured Shorthold Tenancy. Single household, market rent, paid monthly direct to landlord (or via agent). (hover any strategy tab for pros + cons)
Offer (£)
Monthly rent (£)
Local comp range: £1,054–£1,150/mo · n=27
Financing
DepositYour cash in — the rest is the mortgage25% · £60,625
Standard 75% LTV for BTL
Mortgage rate5y fixed5.8%
5-year fixed at 75% LTV — 5.75% (as of 2026-05-20).
Mortgage term (years)
Stress rate6.5%
BoE base + 2pp stress (6.5%)
Acquisition costs
Refurb (£)
Per-property refurb estimate from the element rate-card model (£8,073–£15,070 range), VAT-inclusive
Legal + survey (£)
Standard house — £1,100 legal + £600 survey
Mortgage fees (£)
2% product fee on £181,875 loan + £1,000 booking fee
Running costs
Management10%
Typical BTL agency rate
Void weeks
Typical voids for BTL
Insurance (£/mo)
Typical BTL building+landlord cover for £200K–£400K
Maintenance (£/mo)
Semi/flat: £67/mo proxy
Leasehold costs
Result · Rent it out
Monthly profit
-£296
after mortgage, operating costs & tax
Rent in£1,101/mo gross
£1,059/mo collected · £42/mo lost to voids
Where it goes
£985Mortgage£370Costs
Outgoings exceed rent — you top up £296/mo
Mortgage£985
Costs£370
Management£110
Maintenance£67
Insurance£28
CapEx reserve£55
Voids + council tax£6
Ltd co. accounts£104
Tax—
Shortfall−£296
Returns
Return before costs on price5.45%
Cash return on cash-3.86%
Gross margin£689
Cash needed£92,202
Monthly profit paybackn/a (monthly loss)
Data confidence
Lender stress test
Rent-covers-mortgage check @ stress1.07
Rent-covers-mortgage check FAIL · stress 6.5% (need ≥ 1.45)
Year-by-year Monthly profit (5-yr horizon)
Net Monthly profit after tax. Rent + costs compound at their growth rates; mortgage principal amortises year-by-year for repayment loans.
Mortgage paydownRent profitbefore price growth
Full year-by-year breakdown
| Year | Gross Rent | Op Costs | Mortgage | Equity Built | Tax | Net | Cumulative |
|---|---|---|---|---|---|---|---|
| Year 1 | £13,212 | £4,440 | £11,822 | £0 | £0 | -£3,050 | -£3,050 |
| Year 2 | £13,608 | £4,573 | £11,822 | £0 | £0 | -£2,787 | -£5,836 |
| Year 3 | £14,017 | £4,710 | £11,822 | £0 | £0 | -£2,515 | -£8,352 |
| Year 4 | £14,437 | £4,851 | £11,822 | £0 | £0 | -£2,236 | -£10,588 |
| Year 5 | £14,870 | £4,997 | £11,822 | £0 | £0 | -£1,949 | -£12,537 |
Disposal gain (gross)-£8,393
CGT£0
Net Disposal proceeds£261,046
What we verified
What we verified
41064 ok · 1 caution · 0 fail · 6 unknown
Legal & planning
LeaseholdFreehold
Tenure & planningFreehold
Legal & planning
1 checks- TenureFreehold
Building condition
Energy ratingUnknown
EPC& 2030 deadlineEPC register
EPC band not available in the listing. The 2030 MEES minimum is band C — verify the certificate before offering.
EPC band from listing · verify certificate before exchanging
Find EPC certificate →Cladding safety certificateNot stated on the listing
HeritageNot stated on the listing
Heritage& planning constraintsNHLE register
We don't ingest the NHLE bulk register, so we can't flag listed-building or conservation-area status for this address from our data alone. Use the official registry to verify before exchanging.
Area
Flood riskChecking…
FloodriskEA
Crime riskChecking…
Crimeriskpolice.uk
SchoolsChecking…
Schools& Ofsted catchmentGIAS register
No schools indexed for this postcode sector.
Investor
Tenant profileMixed demand
Tenant profilelikely cohortWR7 4AZ · 2 bed
Primary profile
Mixed demand
Nearest university
for student-let assessment
University of Birmingham · 30.7 km
Reason
Mixed-demand area without a single dominant tenant cohort. Local lettings agent can clarify.
Heuristic from postcode + bedrooms + nearest-university distance · verify locally
Refurb costEstimate ready
Refurb cost& works budgetQ1 2026 rates
New kitchen + bathroom + light replumb + decor.
Total estimate
2-bed · 1-bath · 810 sqft
£22k–£43k
£ per sqft
building cost only
£27–£53
Per-item breakdown (4 lines)
- Kitchen · Full unit replacement£3,840–£8,640
- 1 × bathroom · Full strip + retile£3,325–£6,650
- Paint + decor£5,670–£10,530
- Flooring · Carpet on bedrooms + LVT/laminate downstairs£8,910–£17,010
Guide rates · UK May 2026 · sqft auto-estimated from beds
Tier-based bands — get a builder quote before exchanging.
Rent by the room licensingN/A
Price & sale history86d on marketno cuts yet
Strategy matrix
Rent it out wins — -£296/mo · level with Refurb & refinance
| Strategy | Return before costs on price | Monthly profit | Cash needed | 5y Return on your cash on cash | Risk | Feasibility |
|---|---|---|---|---|---|---|
| ⭐ Rent it out | 5.45% | -£296 | £92,202 | -13.6% | Low | Feasible |
| Housing-benefit rent | 3.45% | -£670 | £92,202 | -38.6% | Med | Feasible |
| Council lease | 3.45% | -£521 | £92,202 | -32.1% | Low | Feasible |
| Refurb & refinance | 5.45% | -£296 | £108,633 | -11.5% | Med | Feasible |
| Short-stay let / Airbnb | — | — | — | — | — | Disabledno local short-let data |
| Buy, improve & sell | 0.00% | -£199 | £273,745 | 6% | Med | Feasible |
| Rent by the room | — | — | — | — | — | Disabledneeds 3+ beds |
Housing-benefit (LHA) scheme detailBRMA Worcester South · cap £698/mo
Housing-benefit rent scheme detail
- Rental Market Area (BRMA):
- Worcester South
- LHA monthly cap:
- £698
- Scheme type:
- nominee
- Premium:
- +0% premium over LHA cap
- Management:
- management covered by council
Ready to move on this deal?
Generates an offer pack with your numbers & sources — take it to the agent.
Pro analysis — outcome range, stress tests & portfolio impact
Local lettings demanddays-to-let · supply now · trend
Rent by the room conversion upside
+£310/mo cash flow vs Rent it out if converted to Rent by the room
11.88% Return before costs on price converted vs 5.45% as-is
As-is Rent it out
Monthly profit-£257
Return before costs on price5.45%
Cash needed£72,523
If converted to Rent by the room
Monthly profit+£53
Return before costs on price11.88%
Cash needed£88,523
Δ vs Rent it out Monthly profit+£310
Show conversion detail
Cannot Rent by the room:Only 2 bed — too small for an HMO (3+ unrelated tenants from 2+ households) without major reconfiguration.
Conversion cost estimate
£44,000
Range: £38,000 – £52,000
Fire safety, plumbing, partitioning, licensing.
Rates as of Apr 2026
£42,690–£80,380full refurb + room split
What's in this cost
- Kitchen£8,640–£17,280
- 1 × bathroom£5,700–£10,450
- Rewire£3,240–£5,670
- Replumb£2,430–£4,860
- Windows£8,100–£14,580
- Paint + decor£5,670–£10,530
- Flooring£8,910–£17,010
Comparables
sold within 0.5 miWide · CV 27.0%Med confidence
Loading nearby sold…
Location & area intelligence
Transport score70 / 100
On the map
- Registered HMOs
- Approved HMO conversions
- Pending HMO applications
Schools & catchment4 schools nearby
Nearby schoolsOfsted-rated, nearest first4 of 5
- GoodUpton Snodsbury CofE Primary SchoolPrimary · Voluntary controlled school · WR7 4NH
- Not ratedCrowle CofE Primary SchoolPrimary · Academy converter · WR7 4AT
- Not ratedFlyford Flavell Primary SchoolPrimary · Community school · WR7 4BS
- Not ratedInkberrow Primary SchoolPrimary · Academy converter · WR7 4HH
Ofsted · postcode-area match. Catchment areas vary year to year — verify with the local council before relying for school admissions.
Tax treatment
Annual gross rent£13,212
Section 24 credit£0
Annual tax due£0
Post-tax Monthly profit annual-£3,558
Exit costs
Projected sale price (5y · 2%/yr growth)£267,740
Capital gain (pre-CGT)£25,240
Sale costs (~2.5%)£6,694
CGT due (Ltd Co 25%)£0
No personal CGT — the gain is taxed at the company level (corporation tax) when the SPV disposes of the property.
Net 5y Monthly profit after CGT-£12,537
Rates as of Oct 2024
Acquisition costs
£92,202cash neededPurchase price£242,500
Deposit (25%)£60,625
Stamp duty+5% additional-property surcharge£14,475
Refurb£10,764
Legal + survey£1,700
Mortgage fees£4,638
Total cash neededdeposit + costs (loan covers the rest)£92,202
Green = verified data. Amber = market typical. Red = our estimate — verify before offering.
About this propertydescription · zoopla
Description& agent copyZoopla
Foxglade House is a two-bedroom property at Blackthorn, forming part of the Discounted Market Value scheme*.
*This is a Discounted Open Market Value property where eligibility criteria applies. Please contact us for more information.
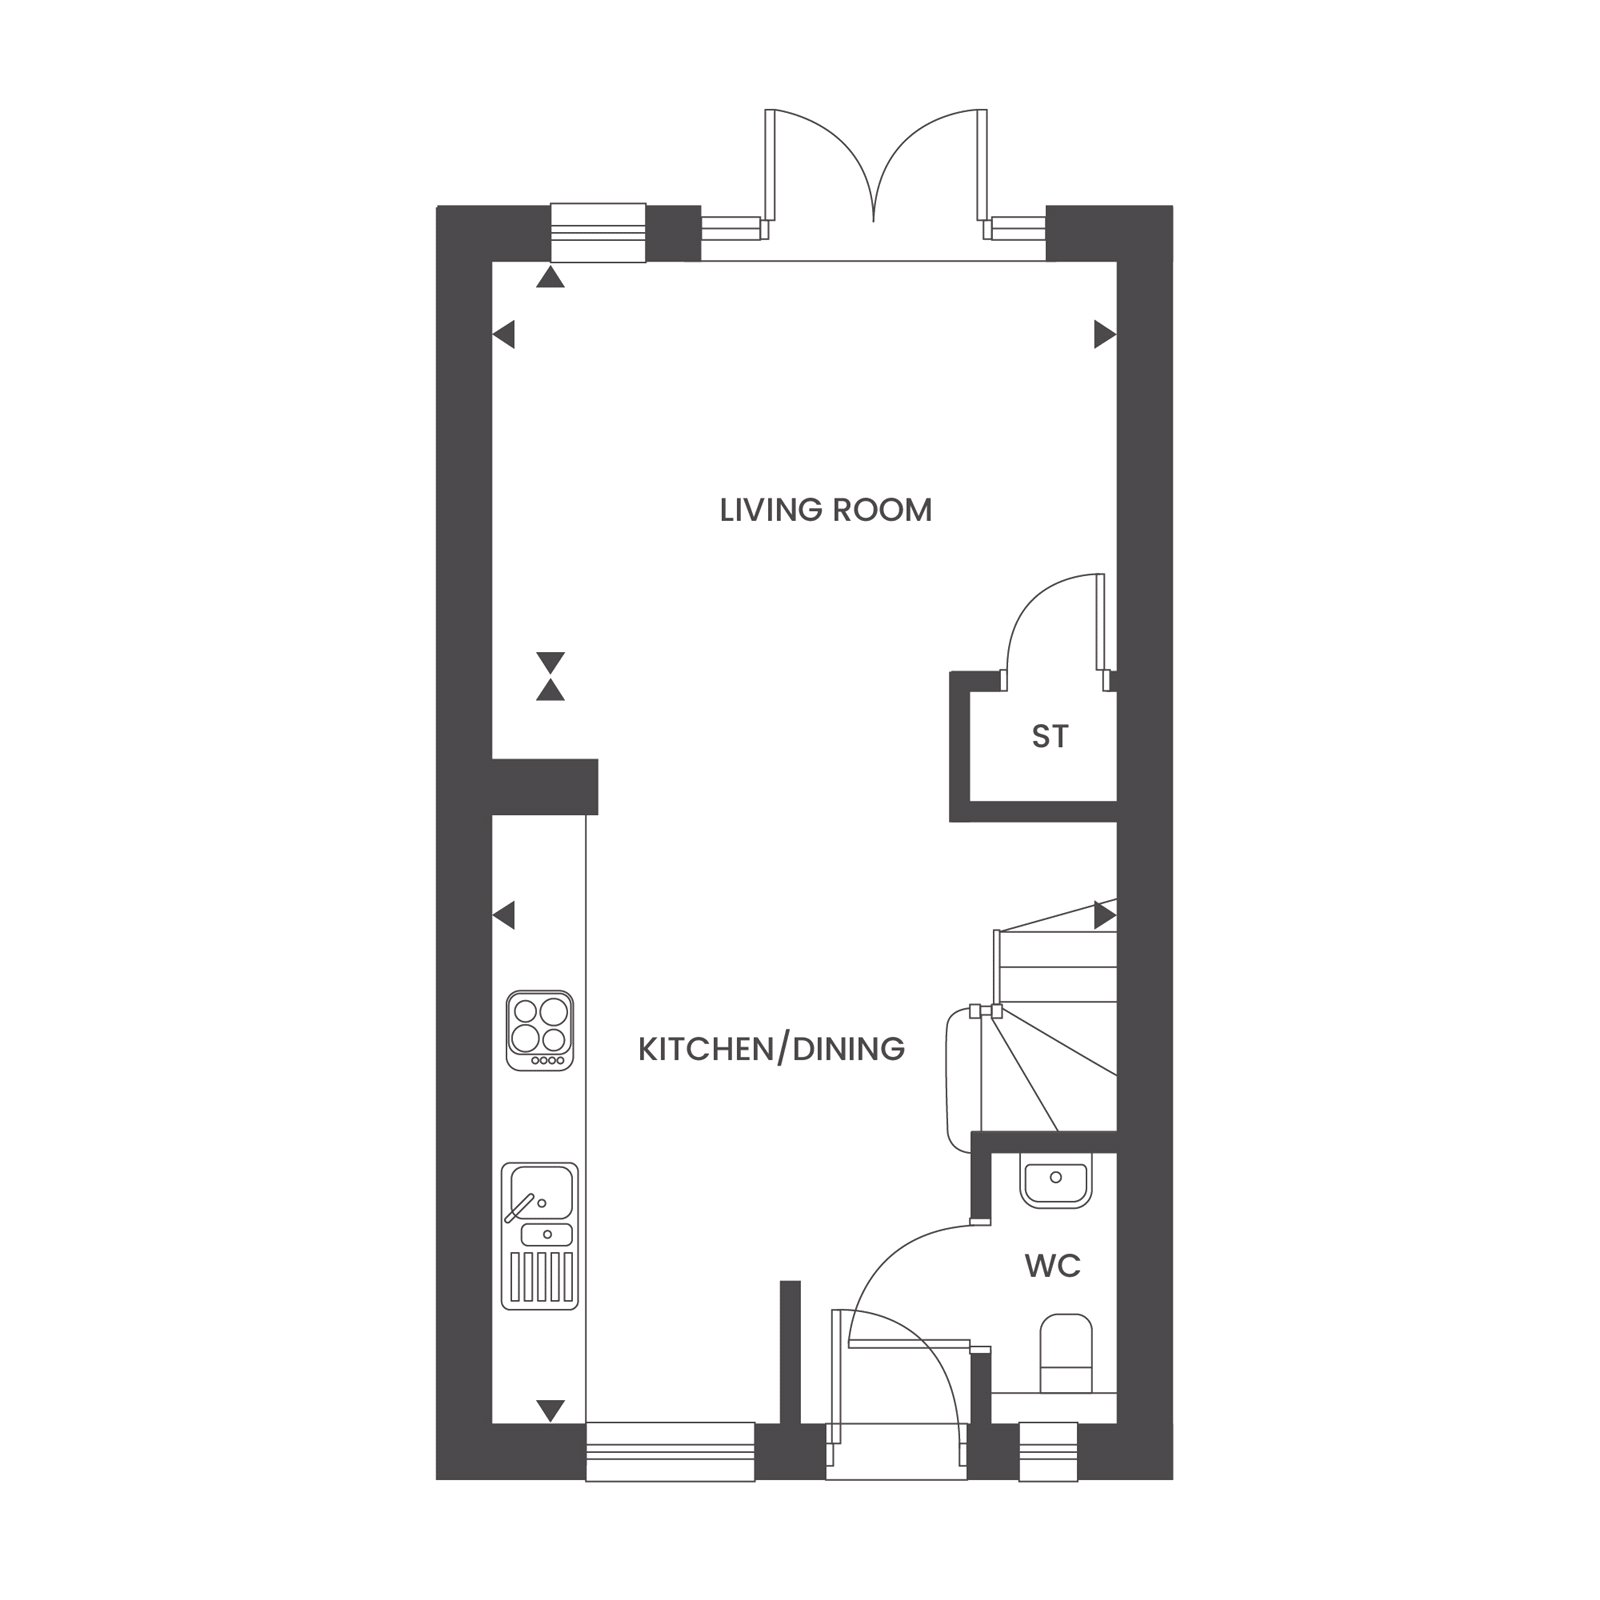
Perfectly blending modern comfort with country charm, this home features a thoughtfully designed open plan ground floor.
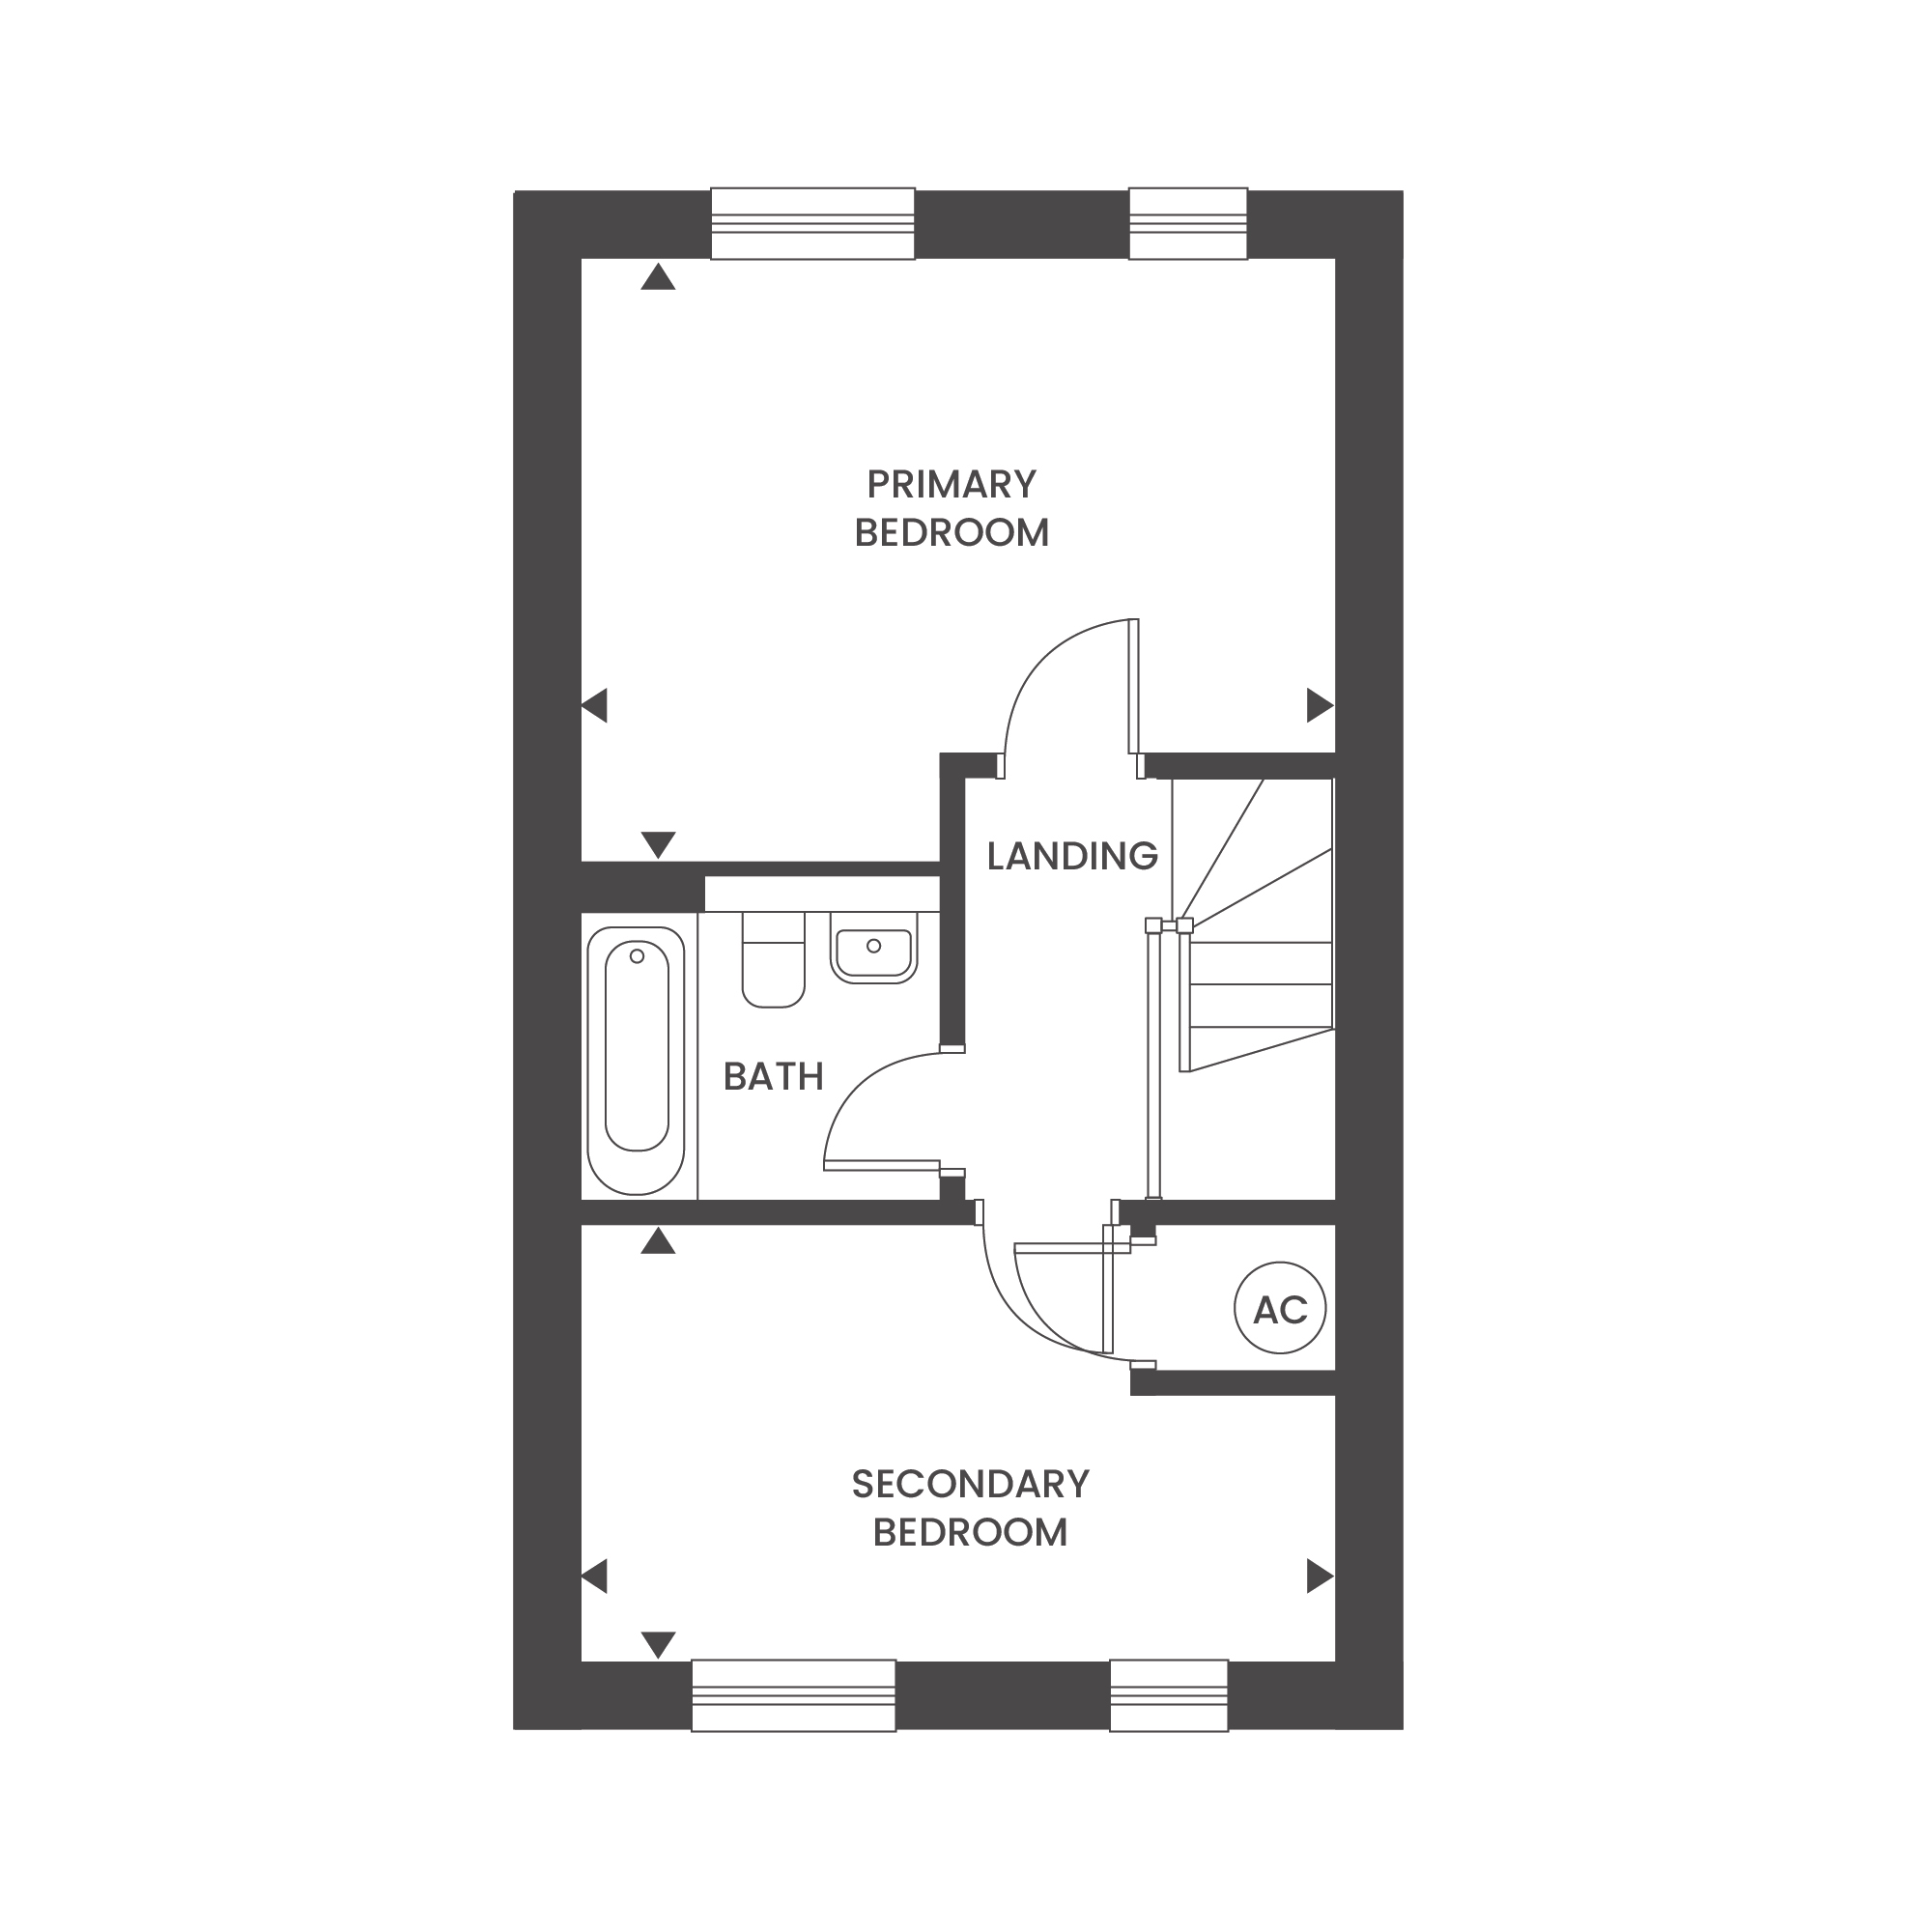
Upstairs, two generously proportioned bedrooms await, including a cost primary suite with a stylish en suite bathroom – id…
Floor plans
Listing metazoopla · Hayman-Joyce Broadway
About this listing
86 days · ZooplaPrice history
5-year price trend
Monthly profit
−£296
Cash needed
£92K
Return after costs
-3.86%
IRR
-3.71%
Listed 86d ago
24 Blackthorn, Crowle, Worcestershire WR7
semi-detached · 2 bed · 1 bath
£242,500
est £1,101 · 5.45% gross
Priced below market
1 / 9
13/100
Marginal
5.45% — verify the rent + comps locally.
Priced below market -25% vs 12 nearby sold (last 12 mo)
Price
£243K
25% below sold comps
Return before costs
5.45%
est rent £1,101/monot enough comparablesRange £1,054–£1,150/mo (Q1–Q3)
Bedrooms
2
1 bath
Energy rating
—
Energy rating
Run the numbers
What-if calculator
Rates as of 20 May 2026Buy-to-Let. Standard rental on an Assured Shorthold Tenancy. Single household, market rent, paid monthly direct to landlord (or via agent). (hover any strategy tab for pros + cons)
Offer (£)
Monthly rent (£)
Local comp range: £1,054–£1,150/mo · n=27
Financing
DepositYour cash in — the rest is the mortgage25% · £60,625
Standard 75% LTV for BTL
Mortgage rate5y fixed5.8%
5-year fixed at 75% LTV — 5.75% (as of 2026-05-20).
Mortgage term (years)
Stress rate6.5%
BoE base + 2pp stress (6.5%)
Acquisition costs
Refurb (£)
Per-property refurb estimate from the element rate-card model (£8,073–£15,070 range), VAT-inclusive
Legal + survey (£)
Standard house — £1,100 legal + £600 survey
Mortgage fees (£)
2% product fee on £181,875 loan + £1,000 booking fee
Running costs
Management10%
Typical BTL agency rate
Void weeks
Typical voids for BTL
Insurance (£/mo)
Typical BTL building+landlord cover for £200K–£400K
Maintenance (£/mo)
Semi/flat: £67/mo proxy
Leasehold costs
Result · Rent it out
Monthly profit
-£296
after mortgage, operating costs & tax
Rent in£1,101/mo gross
£1,059/mo collected · £42/mo lost to voids
Where it goes
£985Mortgage£370Costs
Outgoings exceed rent — you top up £296/mo
Mortgage£985
Costs£370
Management£110
Maintenance£67
Insurance£28
CapEx reserve£55
Voids + council tax£6
Ltd co. accounts£104
Tax—
Shortfall−£296
Returns
Return before costs on price5.45%
Cash return on cash-3.86%
Gross margin£689
Cash needed£92,202
Monthly profit paybackn/a (monthly loss)
Data confidence
Lender stress test
Rent-covers-mortgage check @ stress1.07
Rent-covers-mortgage check FAIL · stress 6.5% (need ≥ 1.45)
Housing-benefit (LHA) scheme detailBRMA Worcester South · cap £698/mo
Housing-benefit rent scheme detail
- Rental Market Area (BRMA):
- Worcester South
- LHA monthly cap:
- £698
- Scheme type:
- nominee
- Premium:
- +0% premium over LHA cap
- Management:
- management covered by council
Year-by-year Monthly profit (5-yr horizon)
Net Monthly profit after tax. Rent + costs compound at their growth rates; mortgage principal amortises year-by-year for repayment loans.
Mortgage paydownRent profitbefore price growth
Full year-by-year breakdown
| Year | Gross Rent | Op Costs | Mortgage | Equity Built | Tax | Net | Cumulative |
|---|---|---|---|---|---|---|---|
| Year 1 | £13,212 | £4,440 | £11,822 | £0 | £0 | -£3,050 | -£3,050 |
| Year 2 | £13,608 | £4,573 | £11,822 | £0 | £0 | -£2,787 | -£5,836 |
| Year 3 | £14,017 | £4,710 | £11,822 | £0 | £0 | -£2,515 | -£8,352 |
| Year 4 | £14,437 | £4,851 | £11,822 | £0 | £0 | -£2,236 | -£10,588 |
| Year 5 | £14,870 | £4,997 | £11,822 | £0 | £0 | -£1,949 | -£12,537 |
Rent by the room upside
What we verified
3207
Legal & planning▾
Article 4HMO restriction lookupUnknown
Rent by the room licensingMandatory if 5+ unrelatedN/A
TenureTenure typeFreehold
HeritageListed building / conservation areaNot stated on the listing
Building condition▾
EPCPostcode estimate — check the registerNot stated on the listing
EWS1External wall safety (cladding)Not stated on the listing
Refurb costBased on beds + baths + sqftEstimate available
Area▾
Crimepolice.uk · monthlyChecking…
SchoolsGIAS · OfstedChecking…
FloodEA Flood Map · England onlyChecking…
Investor profile▾
Tenant profileBeds + postcode heuristicFamily let
Rent by the room feasibilityMin 3 beds for C4 routeBelow threshold
Comparables
sold within 0.5 miWide · CV 27.0%Med confidence
Loading nearby sold…
Location & transport
Tax & exit
Tax bandLtd Co 25%
Mortgage-interest tax rule credit£2,364
Annual rental tax£0
CGT yr 5£0 · company level
5y net total-£12,537
Acquisition costs
25% deposit£60,625
Stamp duty£14,475
Refurb£10,764
Legal + survey£1,700
Mortgage + broker£4,638
Cash needed£92,202
Green = verified data. Amber = market typical. Red = our estimate — verify before offering.
Make an offer
Pro analysis — outcome range, stress tests & portfolio impact
Your notes
Description& agent copyZoopla
Foxglade House is a two-bedroom property at Blackthorn, forming part of the Discounted Market Value scheme*.
*This is a Discounted Open Market Value property where eligibility criteria applies. Please contact us for more information.
Perfectly blending modern comfort with country charm, this home features a thoughtfully designed open plan ground floor.
Upstairs, two generously proportioned bedrooms await, including a cost primary suite with a stylish en suite bathroom – id…
Floor plans
Listing
Sources: Rightmove · HM Land Registry · Ofsted · EA Flood Zones
Estimates not financial advice
Estimates not financial advice