Skip to main contenthow this is calculated →
Year 5 disposal

⊞ View all 5
35/ 100
Weak
7.16% return before costs — verify the rent + comps locally.
Why it works
- 7.16% return before costs — above-market
Why to be cautious
- EPC D — must hit C by 2030 (~£3,000–£7,000)
- Monthly profit −£15/mo — mildly negative — equity build may cover
- No rent comparables — estimate is a rule-of-thumb fallback, not market data. Verify the rent locally before offering.
Property research tool — not a regulated financial service. Numbers are point-in-time estimates; how we decide →
Monthly cashflow
−£15/mo
You top up £15/mo
Price
£220K
No local sold comps to compare
Return · IRR
0.1%/yr
Modest annualised return
Cash to get in
£89K
Deposit + fees + refurb
Return before costs on price 7.16%5-yr return on cash 5%Rent est. £1,313 (£1,254–£1,375)
How we define each return: On price — gross yield = annual rent ÷ purchase price. On cost — net yield ÷ total project cost (price + refurb + fees). On cash — cash-on-cash & ROI ÷ the actual cash you put in (deposit + costs).
What-if calculator
Rates as of 20 May 2026Buy-to-Let. Standard rental on an Assured Shorthold Tenancy. Single household, market rent, paid monthly direct to landlord (or via agent). (hover any strategy tab for pros + cons)
Offer (£)
Monthly rent (£)
Local comp range: £1,254–£1,375/mo · n=27
Financing
DepositYour cash in — the rest is the mortgage25% · £55,000
Standard 75% LTV for BTL
Mortgage rate5y fixed5.8%
5-year fixed at 75% LTV — 5.75% (as of 2026-05-20).
Mortgage term (years)
Stress rate6.5%
BoE base + 2pp stress (6.5%)
Acquisition costs
Refurb (£)
Per-property refurb estimate from the element rate-card model (£11,333–£21,155 range), VAT-inclusive
Legal + survey (£)
Standard house — £1,100 legal + £600 survey
Mortgage fees (£)
2% product fee on £165,000 loan + £1,000 booking fee
Running costs
Management10%
Typical BTL agency rate
Void weeks
Typical voids for BTL
Insurance (£/mo)
Typical BTL building+landlord cover for £200K–£400K
Maintenance (£/mo)
Terraced: £50/mo proxy (shared structure)
Leasehold costs
Result · Rent it out
Monthly profit
-£15
after mortgage, operating costs & tax
Rent in£1,313/mo gross
£1,263/mo collected · £51/mo lost to voids
Where it goes
£894Mortgage£384Costs
Outgoings exceed rent — you top up £15/mo
Mortgage£894
Costs£384
Management£131
Maintenance£50
Insurance£28
CapEx reserve£66
Voids + council tax£5
Ltd co. accounts£104
Tax—
Shortfall−£15
Returns
Return before costs on price7.16%
Cash return on cash-0.21%
Gross margin£879
Cash needed£89,011
Monthly profit paybackn/a (monthly loss)
Data confidence
Lender stress test
Rent-covers-mortgage check @ stress1.41
Rent-covers-mortgage check FAIL · stress 6.5% (need ≥ 1.45)
Year-by-year Monthly profit (5-yr horizon)
Net Monthly profit after tax. Rent + costs compound at their growth rates; mortgage principal amortises year-by-year for repayment loans.
Mortgage paydownRent profitbefore price growth
Full year-by-year breakdown
| Year | Gross Rent | Op Costs | Mortgage | Equity Built | Tax | Net | Cumulative |
|---|---|---|---|---|---|---|---|
| Year 1 | £15,756 | £4,608 | £10,725 | £0 | £80 | £343 | £343 |
| Year 2 | £16,229 | £4,746 | £10,725 | £0 | £144 | £614 | £957 |
| Year 3 | £16,716 | £4,889 | £10,725 | £0 | £209 | £893 | £1,850 |
| Year 4 | £17,217 | £5,035 | £10,725 | £0 | £277 | £1,180 | £3,029 |
| Year 5 | £17,734 | £5,186 | £10,725 | £0 | £346 | £1,476 | £4,506 |
Disposal gain (gross)-£12,886
CGT£0
Net Disposal proceeds£236,825
What we verified
What we verified
51065 ok · 1 caution · 0 fail · 6 unknown
Legal & planning
LeaseholdFreehold
Tenure & planningFreehold
Legal & planning
2 checks- TenureUnknown
- Lease lengthUnknown
Council planning restrictionUnknown
Council planning restrictionRent by the room conversion gatePlanning data
Conversion approvability
Per-property planning assessment
Uncertain50% likely
Confidence: low
- Article 4 direction applies — planning permission required for C3->C4 HMO
- no known HMOs within 100m (below threshold)
- local council HMO approval rate 49% (410 decisions)
- this council refuses HMOs that would sandwich a family home between two HMOs — check both adjoining properties
- NO HMO concentration data for this council: neither a licensed register nor granted change-of-use decisions nearby. This is ABSENCE OF DATA, not absence of HMOs — verify with the council before relying on it
Rent by the room concentration nearby
≈0.0% within 100 m vs 10% policy
Rent by the room restriction
C3 to C4 conversion
Unknown
Confidence
low
Source
No LPA data for this prefix
Rates as of May 2026
Building condition
Energy ratingD
EPC& 2030 deadlineEPC register
▼
ABCDEFG
Current rating
From listing descriptionBand D
MEES 2030 compliance
C required for new tenancies
FAIL
Upgrade to C
estimated cost
£3k–£7k
EPC band from listing · verify certificate before exchanging
Find EPC certificate →Cladding safety certificateNot stated on the listing
HeritageNot stated on the listing
Heritage& planning constraintsNHLE register
We don't ingest the NHLE bulk register, so we can't flag listed-building or conservation-area status for this address from our data alone. Use the official registry to verify before exchanging.
Area
Flood riskChecking…
FloodriskEA
Crime riskChecking…
Crimeriskpolice.uk
SchoolsChecking…
Schools& Ofsted catchmentGIAS register
No schools indexed for this postcode sector.
Investor
Tenant profileFamily let
Tenant profilelikely cohortB9 · 3 bed
Primary profile
Family let
Nearest university
for student-let assessment
Birmingham City · 4.3 km
Reason
3-bed house in a suburban area — family-let demand dominates; check local school catchment ratings.
Heuristic from postcode + bedrooms + nearest-university distance · verify locally
Refurb costEstimate ready
Refurb cost& works budgetQ1 2026 rates
New kitchen + bathroom + light replumb + decor.
Total estimate
3-bed · 1-bath · 990 sqft
£25k–£49k
£ per sqft
building cost only
£25–£49
Per-item breakdown (4 lines)
- Kitchen · Full unit replacement£3,840–£8,640
- 1 × bathroom · Full strip + retile£3,325–£6,650
- Paint + decor£6,930–£12,870
- Flooring · Carpet on bedrooms + LVT/laminate downstairs£10,890–£20,790
Guide rates · UK May 2026 · sqft auto-estimated from beds
Tier-based bands — get a builder quote before exchanging.
Rent by the room licensingStandard rules
HMO licensing5-year licenceCouncil
Licence fee
5-year mandatory
£825–£1,500
Scheme type
Check council
The council's HMO page lists the current mandatory fee plus any additional / selective scheme that catches smaller HMOs.
Mandatory licensing applies to 5+ sharer HMOs (Housing Act 2004)
Find council HMO page →Price & sale history27d on marketno cuts yet
Strategy matrix
Rent it out wins — -£15/mo · level with Refurb & refinance
| Strategy | Return before costs on price | Monthly profit | Cash needed | 5y Return on your cash on cash | Risk | Feasibility |
|---|---|---|---|---|---|---|
| ⭐ Rent it out | 7.16% | -£15 | £89,011 | 5.1% | Low | Feasible |
| Housing-benefit rent | 5.37% | -£344 | £89,011 | -15.5% | Med | Feasible |
| Council lease | 0.00% | -£1,076 | £89,011 | -73.3% | Low | Feasible |
| Refurb & refinance | 7.16% | -£15 | £106,055 | 4.2% | Med | Feasible |
| Short-stay let / Airbnb | — | — | — | — | — | Disabledno local short-let data |
| Buy, improve & sell | 0.00% | -£182 | £255,755 | 3% | Med | Feasible |
| Rent by the room | 9.82% | -£267 | £89,011 | -5.3% | — | Feasible |
Ready to move on this deal?
Generates an offer pack with your numbers & sources — take it to the agent.
Pro analysis — outcome range, stress tests & portfolio impact
Local lettings demanddays-to-let · supply now · trend
Rent by the room conversion upside
+£122/mo cash flow vs Rent it out if converted to Rent by the room
13.09% Return before costs on price converted vs 7.16% as-is
As-is Rent it out
Monthly profit+£3
Return before costs on price7.16%
Cash needed£66,898
If converted to Rent by the room
Monthly profit+£124
Return before costs on price13.09%
Cash needed£82,898
Δ vs Rent it out Monthly profit+£122
Show conversion detail
Conversion cost estimate
£52,800
Range: £46,200 – £61,600
Fire safety, plumbing, partitioning, licensing.
Rates as of Apr 2026
Planning approval likelihood
Uncertain · 50% likely
low confidence
- Article 4 direction applies — planning permission required for C3->C4 HMO
- no known HMOs within 100m (below threshold)
- local council HMO approval rate 49% (410 decisions)
≈0.0% within 100 m vs 10% policy
£56,030–£105,535full refurb + room split
What's in this cost
- Kitchen£9,180–£18,360
- 1 × bathroom£6,150–£11,275
- Rewire£4,400–£7,700
- Replumb£3,300–£6,600
- Windows£11,000–£19,800
- Paint + decor£8,800–£16,500
- Flooring£13,200–£25,300
Comparables
sold within 0.5 miLoading nearby sold…
Location & area intelligence
Transport score100 / 100
On the map
- Registered HMOs
- Approved HMO conversions
- Pending HMO applications
CITY WIDE HMO
≈0.0% within 100 m vs 10% policy
Tax treatment
Annual gross rent£15,756
Section 24 credit£0
Annual tax due£80
Post-tax Monthly profit annual-£263
Exit costs
Projected sale price (5y · 2%/yr growth)£242,898
Capital gain (pre-CGT)£22,898
Sale costs (~2.5%)£6,072
CGT due (Ltd Co 25%)£0
No personal CGT — the gain is taxed at the company level (corporation tax) when the SPV disposes of the property.
Net 5y Monthly profit after CGT£4,506
Rates as of Oct 2024
Acquisition costs
£89,011cash neededPurchase price£220,000
Deposit (25%)£55,000
Stamp duty+5% additional-property surcharge£12,900
Refurb£15,111
Legal + survey£1,700
Mortgage fees£4,300
Total cash neededdeposit + costs (loan covers the rest)£89,011
Green = verified data. Amber = market typical. Red = our estimate — verify before offering.
About this propertydescription · onthemarket
Description& agent copyOnTheMarket
*THREE BEDROOMS* *DRIVEWAY* *GREAT LOCATION*
Oakmans Estate Agents are thrilled to present this three-bedroom mid-terrace property located on Foxwell Road.
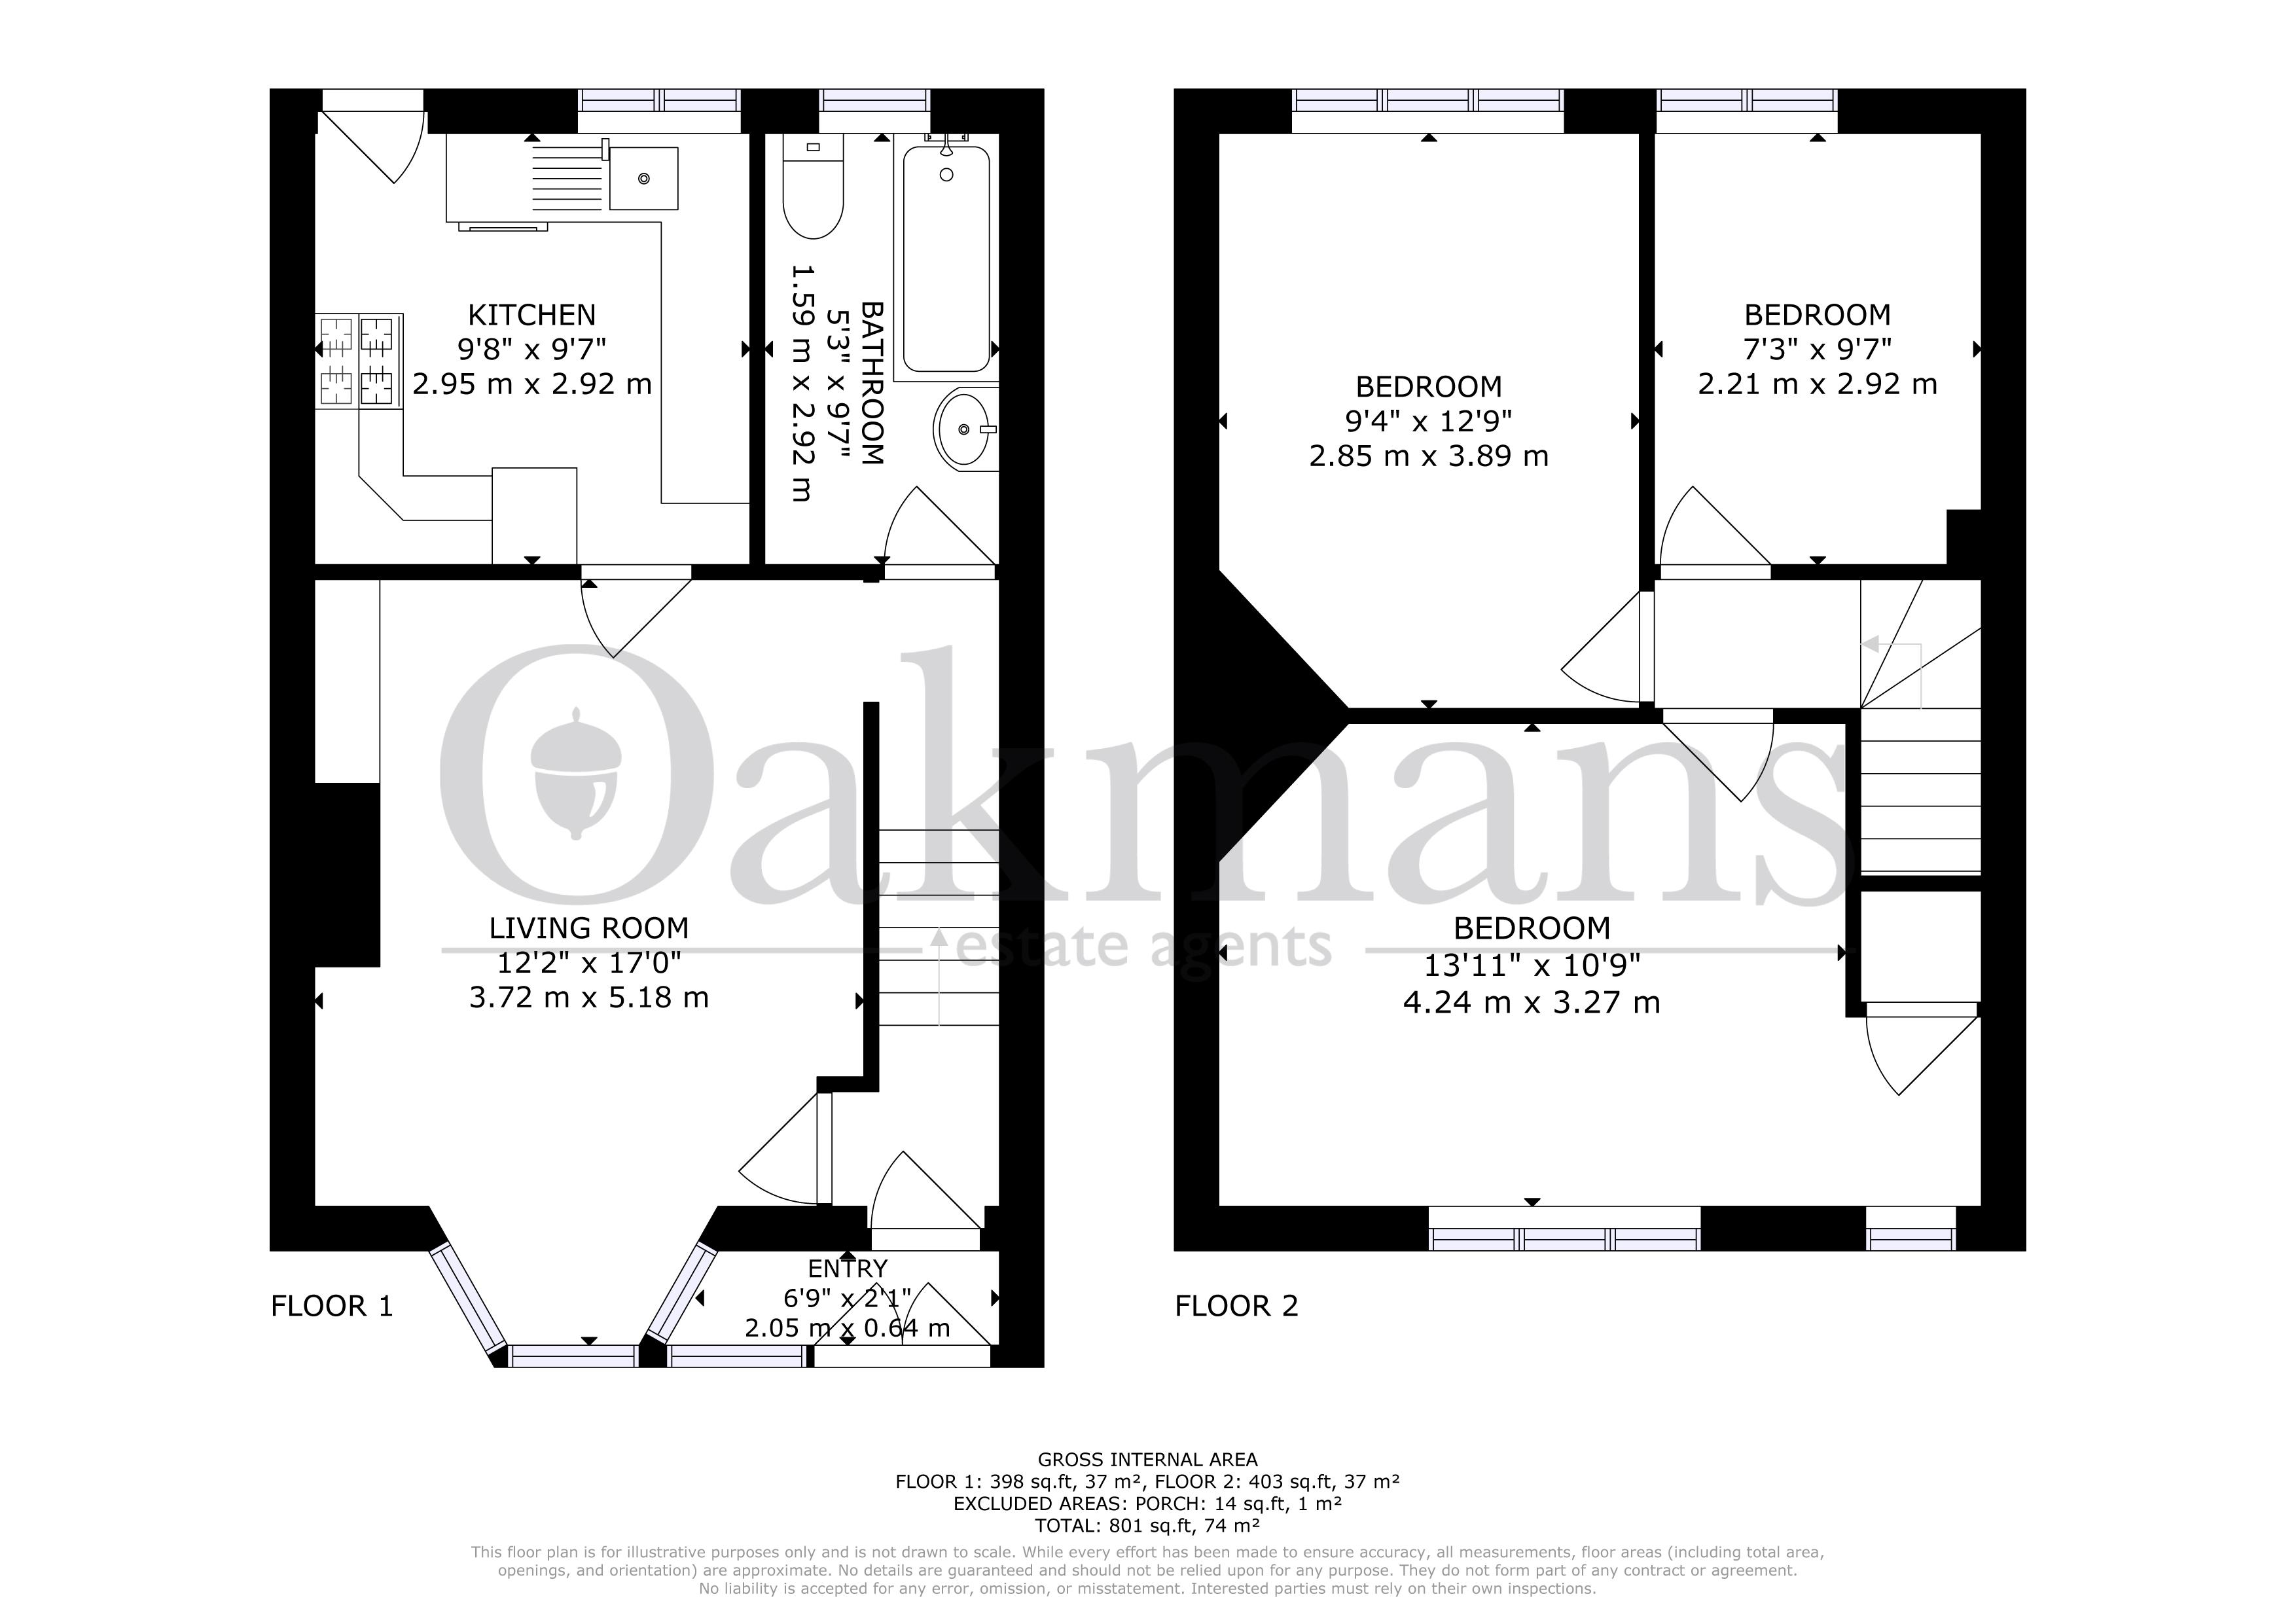
The property briefly comprises of: Entrance Hallway, lounge, kitchen, and downstairs bathroom.
To the first floor, you will find three bedrooms of which two are spacious doubles.
The property benefits from a driveway to the front of the property, spacious garden to the rear and double glazing and central Heating throug…
Floor plans
Nearby active comparables2 rentals
Comparable rentals
B9 · same beds + typeMedian nearby: £1,225/mo · 2 of 2 already let-£88 vs our est
- Pretoria Road, Bordesley Green Birmin…Let3b£1,250/moMay 2026
- Fordrough Lane, Bordesley Green, B9Let3b£1,200/moMay 2026
Other deals nearby
B9 · ±25% priceNo other nearby investment deals matched on postcode prefix + bedrooms.
Listing metaonthemarket · Oakmans Estate Agents - Harborne
About this listing
27 days · OnTheMarketPrice history
5-year price trend
Monthly profit
−£15
Cash needed
£89K
Return after costs
-0.21%
IRR
0.11%
Listed 27d ago
Foxwell Road, Birmingham, B9, Birmingham, B9
terraced · 3 bed · 1 bath
£220,000
est £1,313 · 7.16% gross
EPC D
1 / 5
35/100
Marginal
7.16% — verify the rent + comps locally.
7.16% Return before costs — above-market
Energy rating D — must hit C by 2030 (~£3,000–£7,000)
Price
£220K
Return before costs
7.16%
est rent £1,313/monot enough comparablesRange £1,254–£1,375/mo (Q1–Q3)
Bedrooms
3
1 bath
Energy rating
D
Energy rating
Deal flags1 issue
EPC D — upgrade by 2030
Must reach EPC C by 2030 to let on a new tenancy
Run the numbers
What-if calculator
Rates as of 20 May 2026Buy-to-Let. Standard rental on an Assured Shorthold Tenancy. Single household, market rent, paid monthly direct to landlord (or via agent). (hover any strategy tab for pros + cons)
Offer (£)
Monthly rent (£)
Local comp range: £1,254–£1,375/mo · n=27
Financing
DepositYour cash in — the rest is the mortgage25% · £55,000
Standard 75% LTV for BTL
Mortgage rate5y fixed5.8%
5-year fixed at 75% LTV — 5.75% (as of 2026-05-20).
Mortgage term (years)
Stress rate6.5%
BoE base + 2pp stress (6.5%)
Acquisition costs
Refurb (£)
Per-property refurb estimate from the element rate-card model (£11,333–£21,155 range), VAT-inclusive
Legal + survey (£)
Standard house — £1,100 legal + £600 survey
Mortgage fees (£)
2% product fee on £165,000 loan + £1,000 booking fee
Running costs
Management10%
Typical BTL agency rate
Void weeks
Typical voids for BTL
Insurance (£/mo)
Typical BTL building+landlord cover for £200K–£400K
Maintenance (£/mo)
Terraced: £50/mo proxy (shared structure)
Leasehold costs
Result · Rent it out
Monthly profit
-£15
after mortgage, operating costs & tax
Rent in£1,313/mo gross
£1,263/mo collected · £51/mo lost to voids
Where it goes
£894Mortgage£384Costs
Outgoings exceed rent — you top up £15/mo
Mortgage£894
Costs£384
Management£131
Maintenance£50
Insurance£28
CapEx reserve£66
Voids + council tax£5
Ltd co. accounts£104
Tax—
Shortfall−£15
Returns
Return before costs on price7.16%
Cash return on cash-0.21%
Gross margin£879
Cash needed£89,011
Monthly profit paybackn/a (monthly loss)
Data confidence
Lender stress test
Rent-covers-mortgage check @ stress1.41
Rent-covers-mortgage check FAIL · stress 6.5% (need ≥ 1.45)
Year-by-year Monthly profit (5-yr horizon)
Net Monthly profit after tax. Rent + costs compound at their growth rates; mortgage principal amortises year-by-year for repayment loans.
Mortgage paydownRent profitbefore price growth
Full year-by-year breakdown
| Year | Gross Rent | Op Costs | Mortgage | Equity Built | Tax | Net | Cumulative |
|---|---|---|---|---|---|---|---|
| Year 1 | £15,756 | £4,608 | £10,725 | £0 | £80 | £343 | £343 |
| Year 2 | £16,229 | £4,746 | £10,725 | £0 | £144 | £614 | £957 |
| Year 3 | £16,716 | £4,889 | £10,725 | £0 | £209 | £893 | £1,850 |
| Year 4 | £17,217 | £5,035 | £10,725 | £0 | £277 | £1,180 | £3,029 |
| Year 5 | £17,734 | £5,186 | £10,725 | £0 | £346 | £1,476 | £4,506 |
Rent by the room upside
What we verified
5106
Legal & planning▾
Article 4HMO restriction lookupUnknown
Rent by the room licensingMandatory if 5+ unrelatedCheck LPA
TenureTenure typeFreehold
HeritageListed building / conservation areaNot stated on the listing
Building condition▾
EPC~£3,000–£7,000 to upgrade to CD
EWS1External wall safety (cladding)Not stated on the listing
Refurb costBased on beds + baths + sqftEstimate available
Area▾
Crimepolice.uk · monthlyChecking…
SchoolsGIAS · OfstedChecking…
FloodEA Flood Map · England onlyChecking…
Investor profile▾
Tenant profileBeds + postcode heuristicFamily / Rent by the room
Rent by the room feasibilityMin 3 beds for C4 routeFeasible
Comparables
sold within 0.5 miLoading nearby sold…
Location & transport
Tax & exit
Tax bandLtd Co 25%
Mortgage-interest tax rule credit£2,145
Annual rental tax£0
CGT yr 5£0 · company level
5y net total£4,506
Acquisition costs
25% deposit£55,000
Stamp duty£12,900
Refurb£15,111
Legal + survey£1,700
Mortgage + broker£4,300
Cash needed£89,011
Green = verified data. Amber = market typical. Red = our estimate — verify before offering.
Make an offer
Pro analysis — outcome range, stress tests & portfolio impact
Your notes
Description& agent copyOnTheMarket
*THREE BEDROOMS* *DRIVEWAY* *GREAT LOCATION*
Oakmans Estate Agents are thrilled to present this three-bedroom mid-terrace property located on Foxwell Road.
The property briefly comprises of: Entrance Hallway, lounge, kitchen, and downstairs bathroom.
To the first floor, you will find three bedrooms of which two are spacious doubles.
The property benefits from a driveway to the front of the property, spacious garden to the rear and double glazing and central Heating throug…
Floor plans
Listing
Sources: Rightmove · HM Land Registry · Ofsted · EA Flood Zones
Estimates not financial advice
Estimates not financial advice